Why a bunch of Futures Folks are on that Stage? 

Home » Attain Alternatives Blog » Why a bunch of Futures Folks are on that Stage? 

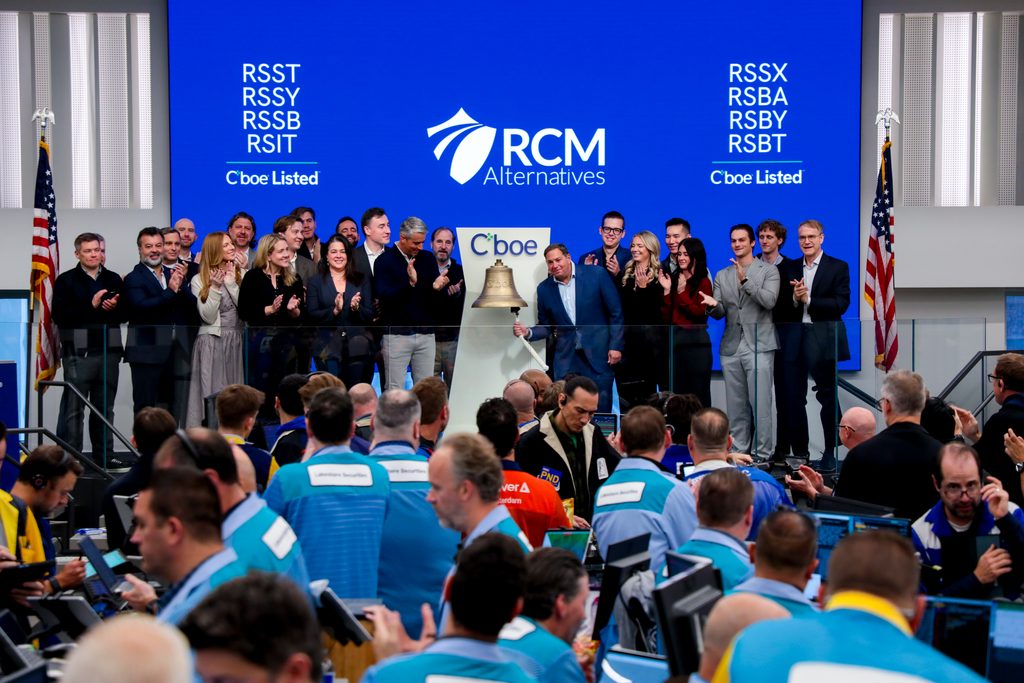
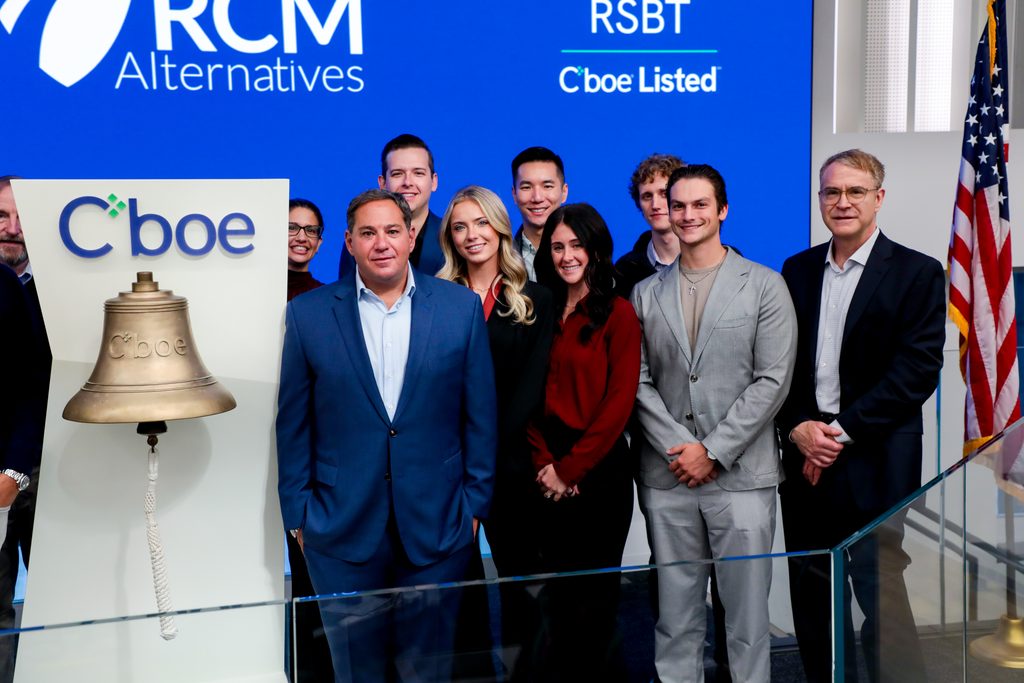
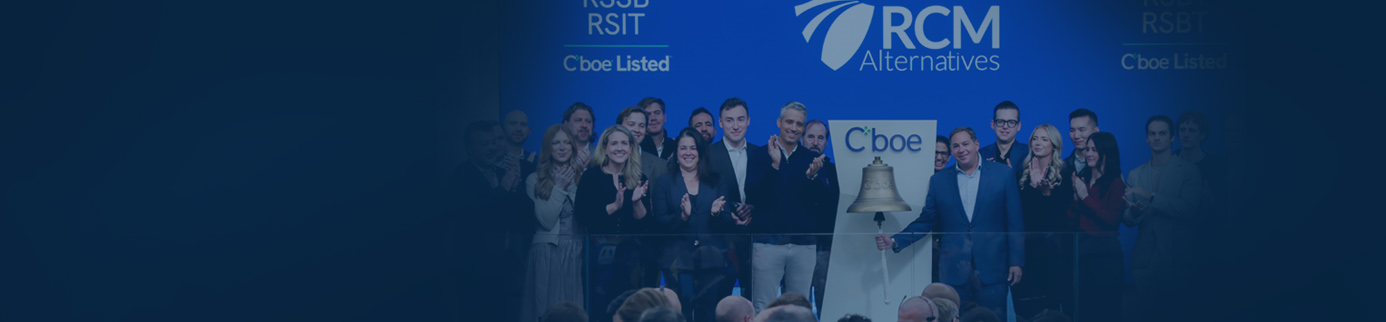
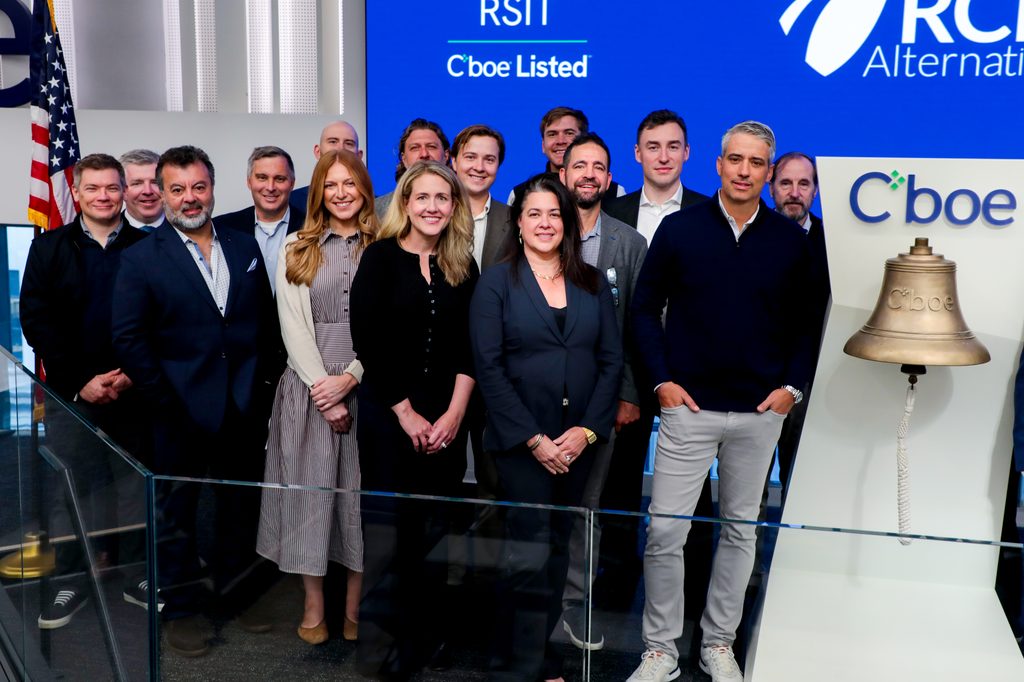
First, the photos: yes, that’s the RCM crew ringing the opening bell at Cboe. It was a fun morning and nobody tripped off the stage. A win! Now for the actual news: futures are moving into ETFs, and for those of us who’ve lived in the managed futures world for years, that’s a big deal. 
Why Should You Care?

Normal people getting into managed futures can be a hassle. You have to deal with:

  • Minimums big enough to buy a boat
  • K-1 tax forms, which tend to show up in late March like a Game of Thrones character you thought was dead
  • Subscription paperwork to rival the Death Star blueprints

That’s not a problem for well heeled investors, family offices, and the like – which we deal with at RCM day in and day out helping make this as easy as possible (see how in our SMA platform here) 

But as easy as we make it, it’s still not a ticker symbol inside a brokerage account and a buy button. So, as the worlds or futures have collided with the world of ETFs, RCM’s had a front row seat, helping many CTAs and pools convert and/or launch ETFs, helping them get global market access, and helping them execute those trades all hours of the day. 

Put it in an ETF 

How’d we get here? For the first two decades, ETFs were the Toyota Corolla of finance: passive, equity, index-tracking, reliable, boring. Nobody was stuffing a trend-following program inside one.

Then the back half of the 2010s happened:

  • The “ETF Rule” (6c-11) turned a multi-year SEC begging process into a standardized ~80-day path from idea to ticker.
  • The Derivatives Rule (18f-4) gave funds a clear framework for holding futures, options, and swaps inside a ’40 Act wrapper. The “you may now enter the building” sign for CTAs.
  • Active got cool. The “will active ETFs be accepted?” debate is over. Gavin Filmore of Tidal told us on the pod that ship sailed years ago, and that his scar tissue from running an index-bound oil ETN when crude went negative is why he’d never build a derivatives product passively again. Flexibility beats rigid rules. CTAs have known that forever.
  • Market makers built the pipes. Five years ago, maybe one or two of them could price an options-heavy or cross-asset ETF second-by-second. Today basically all of them can.

And Gavin’s take on where we are in the ETF story? Inning two or three. Not nine.

So… a lot of smart people stopped trying to fit the square peg of Alts into the round hole of everyday investors and basically said: let’s just put this in an ETF. No futures account, no K-1, no Death Star blueprints. Ticker, brokerage account, buy button.

Look Under the Hood

The ETF wrapper isn’t magic. Keep in mind, Managed futures ETFs ‘vary a lot in how they’re built, what they charge and how many markets they trade. Same story for many Liquid Alts that put hedge fund strategies into a retail product. 


Indeed, we built a whole web page to better categorize and explain what a lot of these products do: see here.

Still, strategies that used to sit behind velvet ropes are now on the same shelf as SPY. That’s worth ringing a bell over.

Related:

Disclaimer Info

The performance data displayed herein is compiled from various sources, including BarclayHedge, and reports directly from the advisors. These performance figures should not be relied on independent of the individual advisor’s disclosure document, which has important information regarding the method of calculation used, whether or not the performance includes proprietary results, and other important footnotes on the advisor’s track record.


The programs listed here are a sub-set of the full list of programs able to be accessed by subscribing to the database and reflect programs we currently work with and/or are more familiar with.
Benchmark index performance is for the constituents of that index only, and does not represent the entire universe of possible investments within that asset class. And further, that there can be limitations and biases to indices such as survivorship, self reporting, and instant history. Individuals cannot invest in the index itself, and actual rates of return may be significantly different and more volatile than those of the index.


Managed futures accounts can subject to substantial charges for management and advisory fees. The numbers within this website include all such fees, but it may be necessary for those accounts that are subject to these charges to make substantial trading profits in the future to avoid depletion or exhaustion of their assets.


Investors interested in investing with a managed futures program (excepting those programs which are offered exclusively to qualified eligible persons as that term is defined by CFTC regulation 4.7) will be required to receive and sign off on a disclosure document in compliance with certain CFT rules The disclosure documents contains a complete description of the principal risk factors and each fee to be charged to your account by the CTA, as well as the composite performance of accounts under the CTA’s management over at least the most recent five years. Investor interested in investing in any of the programs on this website are urged to carefully read these disclosure documents, including, but not limited to the performance information, before investing in any such programs.


Those investors who are qualified eligible persons as that term is defined by CFTC regulation 4.7 and interested in investing in a program exempt from having to provide a disclosure document and considered by the regulations to be sophisticated enough to understand the risks and be able to interpret the accuracy and completeness of any performance information on their own.
RCM may receive a portion of the commodity brokerage commissions you pay in connection with your futures trading and/or a portion of the interest income (if any) earned on an account’s assets. The listed manager may also pay RCM a portion of the fees they receive from accounts introduced to them by RCM.


Limitations on RCM Quintile + Star Rankings


The Quintile Rankings and RCM Star Rankings shown here are provided for informational purposes only. RCM does not guarantee the accuracy, timeliness or completeness of this information. The ranking methodology is proprietary and the results have not been audited or verified by an independent third party. Some CTAs may employ trading programs or strategies that are riskier than others. CTAs may manage customer accounts differently than their model results shown or make different trades in actual customer accounts versus their own accounts. Different CTAs are subject to different market conditions and risks that can significantly impact actual results. RCM and its affiliates receive compensation from some of the rated CTAs. Investors should perform their own due diligence before investing with any CTA. This ranking information should not be the sole basis for any investment decision.


See the full terms of use and risk disclaimer here.